After a Short Sale: When Can I Buy a House
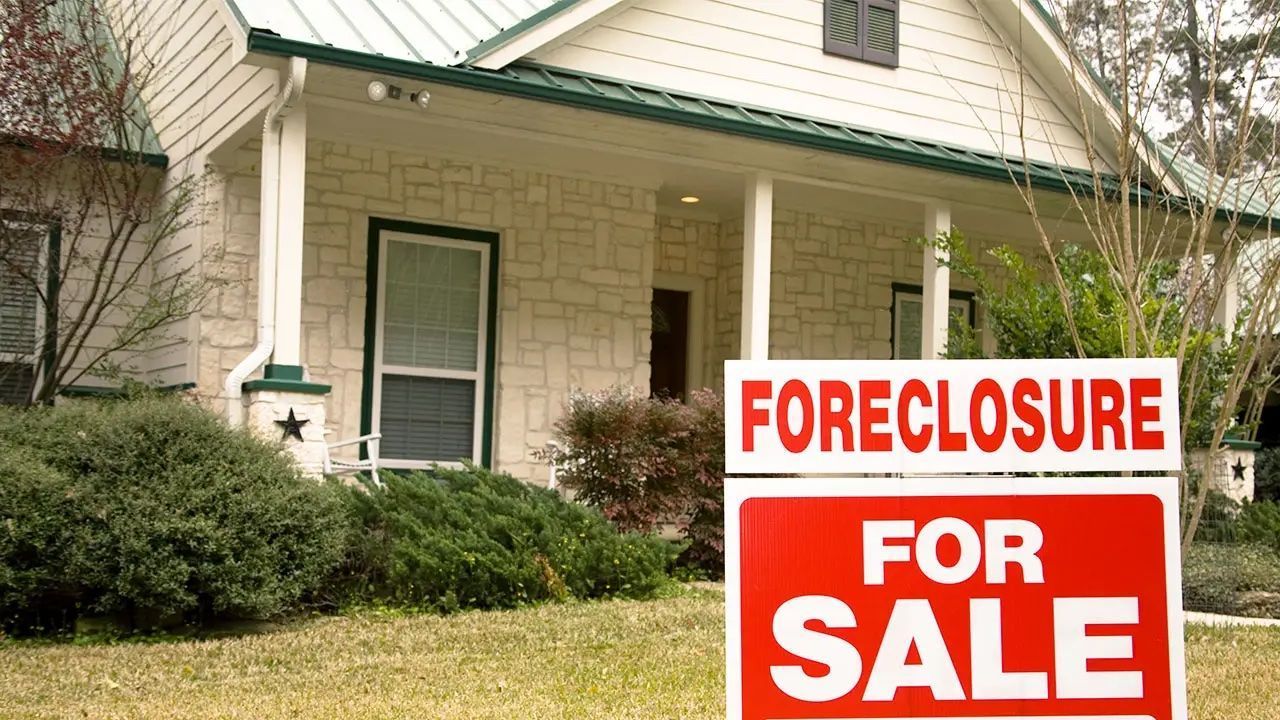
A short sale can be a practical way to escape an unaffordable mortgage, but it also raises an important question: When can you buy a house again? If you’ve gone through a short sale in New York, you may be wondering how long you have to wait before you can qualify for a mortgage again.
At J. Singer Law Group, we help homeowners navigate short sales and prepare for future homeownership. In this guide, we’ll explain how soon you can buy a house after a short sale, what factors affect your waiting period, and steps to speed up the process.
A short sale occurs when a homeowner sells their property for less than the remaining mortgage balance, with the lender agreeing to accept the lower amount as full payment. While it avoids foreclosure, it can still impact your ability to buy a home in the future.
Here’s a breakdown of the standard waiting periods for different mortgage types:
At J. Singer Law Group, we help homeowners navigate short sales and prepare for future homeownership. In this guide, we’ll explain how soon you can buy a house after a short sale, what factors affect your waiting period, and steps to speed up the process.
What is a Short Sale?
A short sale occurs when a homeowner sells their property for less than the remaining mortgage balance, with the lender agreeing to accept the lower amount as full payment. While it avoids foreclosure, it can still impact your ability to buy a home in the future.
How Long Do You Have to Wait to Buy a House After a Short Sale?
The waiting period before you can qualify for a mortgage depends on:- The type of loan you’re applying for
- Whether you had extenuating circumstances
- Your credit score and financial recovery
Here’s a breakdown of the standard waiting periods for different mortgage types:
Tip:
If you want to buy a house as soon as possible, you may be able to qualify for a non-traditional loan (like a Non-QM loan) or provide a larger down payment to offset lender risk.
If your short sale was due to unforeseen circumstances beyond your control, some lenders may shorten the waiting period. Common qualifying extenuating circumstances include: ✔ Serious medical emergency or illness ✔ Job loss or significant income reduction ✔ Death of a primary wage earner ✔ Natural disaster or accident
To qualify for a reduced waiting period, you must:
�55357;�56481; Example: If you lost your job during a recession but found stable employment and rebuilt your credit, you may qualify for a conventional loan in 2 years instead of 4.
Even after the required waiting period, lenders will closely evaluate your financial health before approving a mortgage. Follow these steps to increase your chances of qualifying sooner:
�55357;�56633; Pro Tip: Check your credit report for errors and dispute any inaccuracies.
Your best mortgage option depends on your financial recovery and waiting period:
✔ Conventional Loan: Ideal for buyers with a strong credit score and large down payment after the waiting period. ✔ FHA Loan: Great for those with lower credit scores and smaller down payments. ✔ VA Loan: The best option for eligible veterans, with no down payment required. ✔ Non-QM Loan: A flexible option for those who don’t meet traditional loan criteria.
�55357;�56524; Important: Some lenders impose stricter requirements than federal guidelines. Comparing multiple lenders will help you find the best terms.
If you have access to private financing or alternative funding sources, you may be able to buy a home immediately after a short sale.
A short sale doesn’t mean you’ll never own a home again—it just means you need a strategy to rebuild your financial profile and qualify for a mortgage.
�55357;�56517; Typical waiting periods range from 2 to 4 years, but extenuating circumstances or alternative loan programs can help you buy a house sooner.
At J. Singer Law Group, we specialize in helping New York homeowners navigate short sales and prepare for future homeownership. If you need legal advice or mortgage planning, contact us today for a consultation!
How Extenuating Circumstances Can Reduce Your Waiting Period
If your short sale was due to unforeseen circumstances beyond your control, some lenders may shorten the waiting period. Common qualifying extenuating circumstances include: ✔ Serious medical emergency or illness ✔ Job loss or significant income reduction ✔ Death of a primary wage earner ✔ Natural disaster or accident
To qualify for a reduced waiting period, you must:
- Provide documentation proving the hardship
- Show recovery through stable income and improved credit
�55357;�56481; Example: If you lost your job during a recession but found stable employment and rebuilt your credit, you may qualify for a conventional loan in 2 years instead of 4.
How to Rebuild Your Credit and Qualify for a Mortgage Faster
Even after the required waiting period, lenders will closely evaluate your financial health before approving a mortgage. Follow these steps to increase your chances of qualifying sooner:
1. Improve Your Credit Score
A short sale lowers your credit score, but you can rebuild it by: ✔ Paying all bills on time ✔ Keeping credit card balances below 30% of the limit ✔ Avoiding new debt or late payments�55357;�56633; Pro Tip: Check your credit report for errors and dispute any inaccuracies.
2. Save for a Larger Down Payment
A larger down payment reduces the lender’s risk and increases your chances of approval. Consider saving: ✔ 10–20% down for conventional loans ✔ 3.5% down for FHA loans ✔ 0% down for VA loans (if eligible)3. Maintain Stable Employment & Income
Lenders prefer borrowers with consistent income for at least 2 years. If you’re self-employed, keep detailed tax returns and financial records to show stability.4. Avoid Applying for Too Much Credit
Each new credit application triggers a hard inquiry, temporarily lowering your score. Limit credit applications before applying for a mortgage.5. Work With an Experienced Mortgage Broker or Attorney
A real estate attorney or mortgage broker can help you explore loan programs designed for post-short sale buyers and ensure you meet lender requirements.Which Mortgage is Best After a Short Sale?
Your best mortgage option depends on your financial recovery and waiting period:
✔ Conventional Loan: Ideal for buyers with a strong credit score and large down payment after the waiting period. ✔ FHA Loan: Great for those with lower credit scores and smaller down payments. ✔ VA Loan: The best option for eligible veterans, with no down payment required. ✔ Non-QM Loan: A flexible option for those who don’t meet traditional loan criteria.
�55357;�56524; Important: Some lenders impose stricter requirements than federal guidelines. Comparing multiple lenders will help you find the best terms.
Can You Buy a House Immediately After a Short Sale?
Yes, but only through special financing programs or if you can pay cash. Some non-traditional lenders offer high-interest loans with no waiting period, but they typically require:- A larger down payment (15–30%)
- Higher interest rates
- Proof of financial recovery
If you have access to private financing or alternative funding sources, you may be able to buy a home immediately after a short sale.
Conclusion
A short sale doesn’t mean you’ll never own a home again—it just means you need a strategy to rebuild your financial profile and qualify for a mortgage.
�55357;�56517; Typical waiting periods range from 2 to 4 years, but extenuating circumstances or alternative loan programs can help you buy a house sooner.
At J. Singer Law Group, we specialize in helping New York homeowners navigate short sales and prepare for future homeownership. If you need legal advice or mortgage planning, contact us today for a consultation!
FAQ
Subchapter V Debt Limit & MCA Eligibility: What New York Small Businesses Need to Know in 2026 By Jeb Singer, Esq. , Managing Partner, J. Singer Law Group, PLLC | Admitted: SDNY, EDNY | Last Updated: June 2026
MCA Lawsuit Against Your New York E-Commerce Business: Defenses, Rights & Next Steps By J eb Singer, Esq. | J. Singer Law Group, PLLC | 1 Liberty Street, Suite 2327, New York, NY 10006
Injured at work in Fort Worth? You don't need to know Texas law. Share your story with us for expert legal guidance.
Chapter 11 Automatic Stay: How It Protects Your Business the Moment You File By Ira Reid, Esq . , Partner, Chapter 11 & Subchapter V Restructuring, J. Singer Law Group, PLLC
MCA Default for New York Contractors: Legal Rights, Risks & Defense Strategies By Jeb Singer, Esq., Managing Partner, J. Singer Law Group, PLLC

MCA Funder UCC Seizure in New York: How to Protect Your Business Assets By Jeb Singer, Esq. , Managing Partner, J. Singer Law Group, PLLC

How to Vacate an MCA Judgment in the Bronx: A Step-by-Step Legal Guide By Jeb Singer , Managing Partner, J. Singer Law Group, PLLC | Admitted: New York | Former Law Clerk, Hon. Stuart M. Bernstein, U.S. Bankruptcy Court, S.D.N.Y.
MCA Personal Guarantee Exposure in New York: What Business Owners Must Know Before It’s Too Late By Jeb Singer, Esq. , Managing Partner, J. Singer Law Group, former federal bankruptcy law clerk to Judge Bernstein, U.S. Bankruptcy Court, S.D.N.Y., and MCA defense counsel to New York business owners across Manhattan, Brooklyn, Queens, the Bronx, Long Island, and Westchester.
Commercial Foreclosure Attorney in Queens, NY: Protect Your Property or Enforce Your Rights By Jeb Singer, Esq. , Managing Partner, J. Singer Law Group, PLLC
The LG Funding Recharacterization Test: How New York Courts Decide If Your MCA Is Really a Loan By Stephanie Meltzer, Esq., J. Singer Law Group